Rewards are easy to compare. The harder—and more important—questions concern liability, limits, controls, accounting integration and how the platform behaves when a startup changes shape.
Choose the operating model before the card brand
A startup rarely needs the card with the longest feature list. It needs a programme that matches how the company is funded, who buys, how quickly it closes the books and what happens when an employee needs an exception. Those requirements change as the company hires, expands internationally or moves from founder-led purchasing to departmental budgets.
The comparison should therefore begin with non-negotiables, not provider marketing. Eligibility and liability determine whether a product is viable. Controls and accounting determine whether it scales. Rewards are useful only after the first two tests have been passed.
In brief: A corporate-card decision is a workflow and liability decision with a rewards component—not the reverse.
Start with the operating model
A startup should not choose a corporate card from a rewards headline. The right starting point is a map of how the company spends: who needs purchasing authority, which vendors recur, whether travel is material, how quickly receipts reach accounting, and whether the company pays in full or needs working-capital flexibility.
That map prevents a familiar mistake: buying a card that looks generous in year one but creates manual work at month-end. It also turns a vendor demo into a test of specific workflows rather than a tour of features.
First apply a viability gate
A provider that fails a non-negotiable should not receive a weighted score.
| Gate | Pass condition | Why it comes first |
| Eligibility | Company can qualify under current cash, revenue, funding and geography | A rich feature set is irrelevant if approval is unrealistic |
| Liability | Guarantee and legal obligor match founder and board policy | Changes personal and company risk |
| Liquidity | Repayment timing works in a downside cash-flow month | Avoids a rewards-led cash mismatch |
| Coverage | Currencies, entities and merchant categories fit real spend | Prevents a second card programme from emerging |
| Data exit | Transactions, receipts, rules and audit history can be exported | Protects continuity and future switching |
Compare eligibility, liability and payment terms
The word “corporate” can hide important differences. Ask whether underwriting is based on company cash, revenue, a personal guarantee or a combination. Confirm who is legally responsible for balances, how limits can change, and whether the product is a charge card or revolving credit.
Business-purpose cards do not always carry the same protections as consumer cards. The CFPB’s Regulation Z materials show that some issuance and unauthorized-use provisions extend to business-purpose cards, while broader consumer protections may not. Founders should read the actual agreement and obtain professional advice when liability is unclear.
A company-defined corporate-card decision matrix
Illustrative weights only. A startup should change them before scoring any vendor.
| Decision area | Illustrative weight | Evidence to collect |
| Eligibility and liability | 20% | Underwriting basis, guarantee, legal obligor, limit-change terms |
| Payment terms and liquidity | 15% | Charge or revolving structure, statement timing, repayment mechanics |
| Spend controls | 20% | Limits, merchant rules, approvals, virtual cards, exception handling |
| Accounting workflow | 20% | Receipt capture, coding, sync failures, audit trail, multi-entity support |
| Total economics | 15% | Fees, realistic rewards, interest, FX, surcharges, adjacent software replaced |
| Support and portability | 10% | Issue resolution, exports, API access, implementation ownership |
Test controls before rewards
Controls determine whether a card program scales. Useful questions include whether a company can set limits by employee, team, merchant or time period; issue single-purpose virtual cards; require pre-approval; block categories; and freeze a card without interrupting unrelated spend.
A neutral corporate-card comparison should therefore evaluate the control model alongside rewards and limits. A platform may be strong for a travel-heavy venture-backed team and weak for an ecommerce company with concentrated advertising or shipping spend. “Best” is shorthand for fit.
Ask for evidence, not a checked feature box
A comparison sheet should distinguish availability from operating quality. “Accounting integration” might mean a nightly export, or it might mean entity-aware mappings, receipt matching, error queues and reversible sync. “Spend controls” might mean a fixed card limit, or a policy engine with merchant, time, project and approval rules. For each important capability, request the configuration screen, an export, the exception trail and a live test.
For architecture and design studios, the precision of these integrations can be critical. Managing project-specific budgets, client billing, and material costs requires robust data flows that can categorize expenses by project, phase, or even specific design elements. The ability to track and export detailed financial data ensures that project profitability is accurately measured and client invoices reflect true costs, supporting transparent and efficient practice management.
The startup should also identify manual services performed during the sales process. If the vendor cleans data, maps the ledger or resolves failed transactions behind the scenes, record who will own that work after launch and whether it is included in the price.
Measure accounting friction
Ask the controller to own this part of the evaluation. The team should test receipt capture, entity and department coding, sync behaviour with the accounting system, correction workflows and the quality of the audit trail. A direct integration is not enough if failed syncs are hard to diagnose or if dimensions do not map cleanly.
In design and architecture, where project-based work often involves numerous vendors, contractors, and material suppliers, the clarity of financial records directly impacts project success. Seamless integration with project management and accounting software helps maintain a clear financial picture, allowing design teams to focus on creative output rather than administrative overhead, and ensuring compliance with financial regulations for complex, multi-stage projects.
Recordkeeping also matters. The IRS notes that supporting documents for business expenses should identify the payee, amount, proof of payment, date and business purpose; statements alone may not substantiate every element. The card workflow should make that evidence easier to collect, not merely move transactions faster.
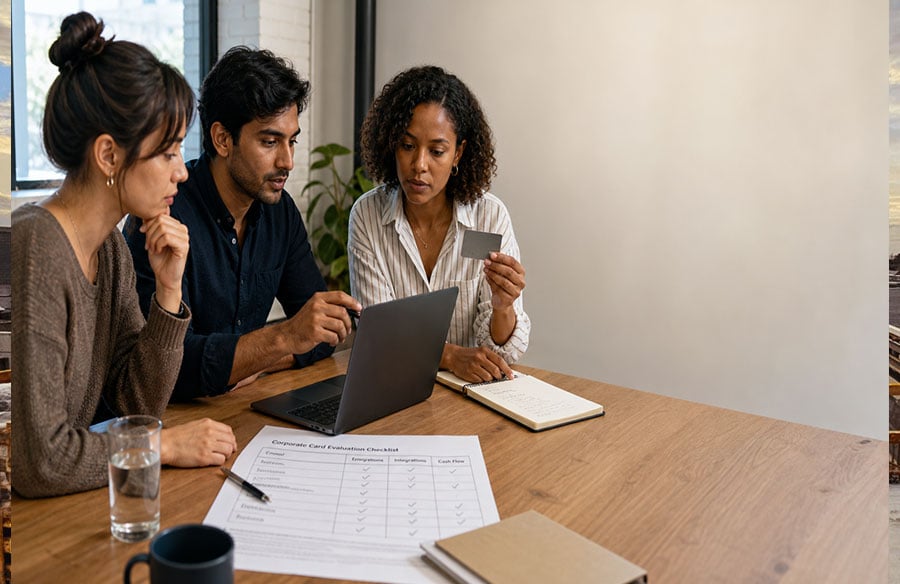
Figure: A company-defined comparison scorecard.
Run four controlled tests before signing
A vendor demo should become a short operational trial. Test the events that create work for finance:
- A legitimate purchase above an employee’s normal limit that requires a documented exception.
- A missing receipt and a receipt whose merchant name differs from the card descriptor.
- A subscription renewal that should be reassigned, reduced or cancelled.
- A failed accounting sync that needs diagnosis without vendor intervention.
- An employee departure with active physical and virtual cards.
Model total value under three scenarios
Run the numbers for today’s company, a downside case and the company you expect in 18 months. Include annual and employee-card fees, expected rewards at realistic redemption values, foreign transaction costs, interest if a balance might be carried, accounting time, and the cost of replacing adjacent tools.
Then run a pilot. Give a small group real cards, connect a sandbox or secondary ledger, and close one month. The winning platform is the one that preserves control while reducing work under normal and messy conditions—not the one with the longest feature list.
A 30-day evaluation plan
In week one, document current spend, approval paths, accounting dimensions and the pain points employees report. In week two, configure two shortlisted platforms with the same policies and issue cards to a small, representative group. Include one frequent traveller, one purchaser, one manager and the person who closes the books.
During weeks three and four, run ordinary transactions plus controlled tests: a purchase above a limit, a missing receipt, a subscription renewal and a legitimate exception requiring approval. Verify what the employee sees, how quickly finance can intervene and what reaches the ledger. Do not use a production test that could create an unrecoverable loss.
At the end, score the platforms using evidence from the pilot. Record any workaround the vendor performed manually, because it may not scale after onboarding. A disciplined trial often changes the ranking: the easiest demo is not always the easiest month-end.
Do the economics under three operating scenarios
A single annual-spend estimate hides the risks that change the decision. Model a normal case using current eligible spend, a downside case with lower rewards and higher foreign-exchange or software costs, and a growth case with more cardholders, entities and approval layers. Include fees, repayment timing, expected redemption, financing cost, implementation labour and any software genuinely replaced.
The winning platform may not produce the highest headline reward. A lower-reward programme can create more value if it reduces close work, prevents policy leakage and supports the company’s liability and liquidity constraints. Keep those components separate so a subjective estimate for time saved cannot disguise a weak card programme.
Finish with a written decision record
The final page should state the non-negotiables, weights, observed test results, unresolved risks and the owner of each assumption. Include the reason the runner-up lost and set a review date tied to a real event such as a funding round, international launch or accounting-system change. This makes the choice reviewable without pretending it will remain correct forever.
A decision founders can defend
Document the final choice in a one-page scorecard with non-negotiables, weights and known trade-offs. That record is valuable when the company raises capital, hires a controller or revisits the decision after growth.
A corporate card sits at the junction of credit, payments, employee behaviour and accounting. Choosing it deserves the same discipline a startup applies to its cap table or payroll system.